July 01, 2019

HONMA Golf, Governance and Corporate Finance

In this post I will try to give the big picture of HONMA Golf, that is to say, an analysis of Corporate Governance and Corporate Finance and what this analysis would recommend to the management which could be sound arrogance, but this is a part of the analysis exercise, no more, no less.

It could be said that this post should have been posted before valuation, but I have two reasons why I didn’t it, the first one is that Corporate Finance is a tedious work and sometimes could distract from the main story of the company, and the second reason is simple: link stories and numbers are much more fun.

Let´s start...

Corporate Governance (Ownership & Board)

At March 30th, 2019, HONMA had 609.05 millions of outstanding shares and the significant investors in HONMA are:

  • Kouun Holding Ltd (53.2%): Private holding controlled by the founder Mr. Jian Guo Liu, (Individual Large Hdg)
  • Charoen Pokphand Group Company Ltd (15%): Thai private company controlled by “Chearavanont” family, (Individual Large Hdg)
  • Itochu Corp (6.29%): Japanese public company trading in Tokyo Stock Exchange, (Individual Large Hdg)
  • Fosun International Ltd (5.85%): Chinese public company trading in Shangai Stock Exchange and controlled by Mr. Guo Guangchang (Institutional Large Hdg)


These four major investors represent 80.2% of the company, leaving a free float of around 20% available to other holders (private investors, institutional investors and banks with less than 5% of the outstanding shares).

The firm has significant individual holdings and small institutional holding, therefore the marginal investor is “Kouunn Holding Ltd” controlled by Mr. Jian Guo Liu, and I will assume that “Kounn” is diversified.

The board is composed of the 8 members described as follow:


Some conclusions of the table above:
  • Majority of directors are insiders
  • President and Chairman are the same person
  • Not all committees are entirely of outsiders


With all these conclusions above I can´t consider that the board of HONMA is effective in acting as a counterweight to a powerful Chairman/President, Mr Liu Jianguo. Consequently I would recommend to revert these 3 points.

Risk (Cost of equity, Cost of debt & Cost of capital)

As a risk free rate, I used the 10 year Japan government bond rate of -0.157% less Default Spread for Japan of 0.68%, resulting -0.84%.


The average global unlevered beta is 0.83 for Recreation business, as HONMA operates in only one business, I will take an unlevered beta for HONMA  of 0.83. Taking into account debt/equity ratio -lease commitments adjustments- gives me the levered beta of 0.87.

To estimate the equity risk premium of HONMA, I looked at HONMA's revenues by regions and applied the equity risk premiums for each of these countries. This results in a weighted ERP for HONMA of 6.67%. 

Based on the above risk free rate, beta and ERP, HONMA´s cost of equity in JPY is 4.99%.

The company provides with information about its pre-tax cost of debt between 0.33% and 0.51%, averaging  0.42%.

The market value of debt outstanding is Ұ4,986 million and the market value of equity is Ұ61,581 million.

Based on a cost of equity of  4.99% and a cost of debt of 0.42%, the cost of capital of HONMA is 4.64% and HONMA should only undertake investments that return at least 4.64%, the minimum acceptable hurdle rate.

Capital Structure

HONMA´s debt to capital ratio is 9.11%, lower than average global industry (23.12%) and probably underlevered.


All debt is short-term debt with maturity less than one year. The debt is mainly in USD (62%) and JPY (23%), the rest of debt (14%) is distributed in HKD, TWD, RMB and others. All HONMA debt has a floating rate between 0.33%-0.51%.

A certain level of debt for HONMA has the following advantages and disadvantages:


Optimal Capital Structure & Financing Changes

HONMA´s current debt-capital ratio is 9.19%.


Simulating across various debt-to-capital ratios, and taking to account changes in the levered beta, cost of equity, interest payments, interest coverage ratios, cost of equity, etc, the following is revealed:

Optimal debt-capital ratio (60.00%) is greater than current, and it seems that HONMA is underlevered.

Given its shareholder structure (Mr. Liu Guo hold 53.2% of common shares) and its market capitalization (over HK$4.2 billion), HONMA seems an unlikely target for a takeover.

An EVA to equity and EVA to capital positives (see previous post), could indicate that HONMA has good projects and I would recommend to the company, take additional suitable projects with returns above its hurdle rate, and finances them with additional debt.
I would advise HONMA to align the debt maturities with the durations of those projects (and the respective assets generating cash flows).

For all projects, I would assume lifecycles around 3 years, and thus recommend financing them with longer-term debt and with a mix of currencies related to the project costs and expected revenues.

The more uncertainty HONMA sees in the future and in its newly started projects, the more it should use floating-rate debt. 

By raising its debt-to-capital ratio up to around 60%, HONMA could increase its firm value from Ұ52,475 million to Ұ53,053 million, and its stock price from Ұ99.43 to Ұ100.37 (+1%). By doing this, HONMA’s cost of capital would drop to 4.48%, really not too much. Thus I don´t see any significant reduction in the cost of capital to justify any increment on debt.

Dividend Policy

HONMA has returned Ұ6,874 million to stockholders in the last three fiscal years (analyzed from 2016/2017 to 2018/2019) having generated Ұ3,250 million of FCFE in that period.


The reduction of debt and the big increment in working capital in period 2016/2017 explain a negative FCFEE for that fiscal year and the reduction of the aggregate. There isn’t any indication that HONMA plans to stop its dividends, therefore the dividend policy in fiscal year 2016/2017 should not occur again.

June 30, 2019

HONMA Golf, expanding premium niches in the market

Overview
HONMA Golf Ltd –incorporated in Cayman Islands, listed on Hong Kong Stock Exchange with ticker 6858 and headquartered in Tokyo– is a prestigious and iconic brand in the golf industry.
The company utilizes innovative technologies and traditional Japanese craftsmanship to provide golfers across the globe with premium, high tech and the best performing golf clubs, balls and accessories.
The Group’s sales and distribution network consists of HONMA-branded self-operated stores as well as distributors, and develops and manages its sales and distribution network on a country-by-country basis to cater for the specific retail landscape and consumer demographics.
As the only vertically integrated golf company with in-house design, development and manufacturing capabilities, a strong retail footprint in Asia and diverse range of golf clubs and golf related products, HONMA is positioned to grow its business in Asia and beyond, benefitting from the return of golfers in mature golf markets such as US and Japan and from increased participation in golf´s new markets such as Korea and China.
As of Jun 17th, 2019, HONMA´s market capitalization was HK$4,263 million with 609 million shares outstanding at a value of HK$7.00 each.
Back and Current Story
Founded in 1959, HONMA fell on hard times with the collapse of Japan´s bubble economy in the 1990s. It had overinvested in golf courses and made other missteps. In 2005, it filed for bankruptcy protection, and in 2010 – in what many Japanese viewed as a painful indignity – it was bought by a Chinese fund run by businessman Liu Jianguo who also operates a Shanghai company that makes hair dryers and rice cookers. Yet Liu Jianguo became Chairman and President of HONMA since then.

In October 2016, the company went public at HK$10 without fanfare and Liu Jianguo turned HONMA around by revamping its sales strategy since then –Ұ18,525 millions revenues in period 2014-2015 and Ұ27,770 millions revenues in period 2018-2019, so a CAGR 4 Years of 10%–.
Although revenues has been decelerated from 21% in 2016 down to 6% in 2019, EBIT margin has maintained around 20% which makes sense, as I will describe later, with the strategy of the company.

The charts below set forth the breakdown by region and product of the total sales in 30mar19.
As we see HONMA have a strong presence in its home markets of Japan, Korea and China (including Hong Kong and Macau), while clubs represents by product the most important source of revenues.
Global Golf Products Industry Overview and where fit HONMA
Golf is a sport which boasts worldwide popularity and is enjoyed by millions globally. The sport involves players using various types of clubs to hit balls into a series of holes with the aim of minimizing the number of strokes required. To play golf, a golfer needs a set of clubs of various lengths and sizes, a set of golf balls and related accessories such as gloves and bags. These products make up the core of the global golf products market. Golf apparel includes clothing and shoes targeted at the golf lifestyle market and forms another important segment of the golf products market.
Key market players supporting the market expansion significantly include Callaway Golf Company, Amer Sports Corporation, MIZUNO Corporation, TaylorMade Golf Company, Inc., Acushnet Holdings Corp., Roger Cleveland Golf Company, Inc., Parsons Xtreme Golf, LLC, Bridgestone Sports Co., Ltd., Honma Golf Co., Ltd., and Epon Golf.
Although global retail sales has been stagnated since 2014 (US$13.4B), HONMA has been able to increase its market share from 1.5% at 2015/2016 to 1.9% at 2018/2019.
The following factors are expected to be key drivers of growth for the golf products industry over the next several years:
  • New Markets and Demographics. Golf has traditionally been under-penetrated in emerging markets. In recent years, more people in emerging markets, especially in Asia, have started to play the sport, driven by increasing disposable income, higher standards of living and greater emphasis on leisure activities. Meanwhile, golf has also gained greater popularity among women and the younger generation worldwide, as a result of the increasing perception of golf as a “lifestyle sport”, a new generation of young golfers coming to prominence on the professional circuit, and additional marketing efforts by golf brands towards these demographics.
  • “Lifestyle Sport” Proposition. Positioned as a “lifestyle sport” with an element of prestige that accommodates competition, entertainment and physical exercise, golf appeals to modern consumers who pursue a higher quality lifestyle with an increasing awareness for health and wellness.
  • Golf ’s Return to the Olympic Games. The reinstatement of golf at the 2016 Olympic Games significantly raised the profile of the sport worldwide. As we edge closer to the 2020 Tokyo Olympic Games, global attention is slowly starting to focus on Olympic qualification. With Japan hosting the 2020 Olympics, the golf markets in Japan and other parts of Asia are expected to receive a significant boost in the build-up to the Olympics.
  • Digitalization of Retail Channels. Digital retail channels such as e-commerce, mobile commerce and social commerce now address consumers’ purchase preferences, which were predominantly restricted to brick and mortar stores in the past. These emerging channels play vital roles in penetrating different consumer segments.
  • Technological Innovation. Golf products development has always been driven by technological innovations over the years. Further developments in clubs, balls and related products are expected to make the game more accessible, enjoyable and exciting, while continuing to attract new players.

According to HONMA Golf, consumer preferences for golf clubs can be classified under two key dimensions:
  • the willingness to spend, or acceptable price of clubs; and
  • the degree of enthusiasm for golf. The degree of enthusiasm can be measured by the consumer’s skill and participation level, which is score for playing one round of golf, as well as number of rounds played within a particular time period.

Based on the two key dimensions described above, the golf clubs market can be segmented into the 9 Key Segments, each consisting of a unique type of golf club consumer.
HONMA currently offers golf clubs mainly under three major product families, namely BERES, TOUR WORLD and BeZeal, each targeting specific consumer segments:
  • BERES golf clubs target consumers in Segment 2, which is the Group’s traditional customer base and comprises affluent consumers willing to pay a premium price for golf clubs
  • TOUR WORLD golf clubs target consumers in Segment 6, which comprises golf enthusiasts who place a higher emphasis on performance
  • Be ZEAL golf clubs target consumers in Segment 5, which comprises beginner golfers who are looking to improve their performance.

Segments 5 and 6 are experiencing faster growth rates compared to the overall growth rates of major golf markets.
How good are the existing investments
On March 30th, 2019, HONMA presented its results for the last fiscal year. The company earned  ¥4,732.0 million as after‐tax operating income on a book value of capital invested of ¥16,357.6 million, while the net income was ¥4,127.5 million on a book value of equity of ¥28,050.0 million.
The after‐tax return on capital based upon these numbers is 29% and the return on equity is 15%.
With after tax return on capital of 29% and relative to the cost of capital of 4.64%, HONMA seems to be earning an excess return of 24.29%. With a return on equity of 15% and relative to the cost of equity of 4.99%, HONMA earns an excess return of 9.72%.

Therefore  HONMA has a positive amount Economic Value Added both to capital and equity:
Since IPO in 2016, HONMA has focused in targeting niches of golf market which are willing to pay a premium for golf clubs. In order to increase sales in these segments, the company has launched several golf clubs families in the last 3 years to align with its target consumer´s preferences. This growth strategy can explain both high ROC and ROE.
Valuation
A plausible story for the future of HONMA could be an exclusive golf company, with low production and medium/high prices. The benefits of this strategy are high operating margins partly because of the high prices, and partly because the company does not have to spend much more on expensive ad campaigns or selling than it is doing now (currently 11% of revenues). It also will keep reinvestment needs to a minimum, since capacity expansion will not be necessary, though the company will continue spending on R&D to preserve its edge (currently 1% of revenues). In addition, by focusing on people with more purchasing power around the world, HONMA may be less affected by macroeconomic forces than other golf companies.

The inputs into my valuation reflect the story, with low revenue growth, high margins and low reinvestment, driving value:
  1. Revenues growth of 5% a year for next 5 years, scaling down to the current risk free rate -0.84% in year 10
  2. HONMA´s EBIT Margin stays at 20%, the current margin in last year
  3. Sales/Invested Capital stays at 1.52 reflecting the little need for capacity expansion
  4. Cost of capital of 4.67%, scaling down to global industry average

Other relevant inputs to be assumed:
  1. Many growth companies fail, especially if they have trouble raising cash. In case of HONMA, I will give a 10% probability of failure with a distress proceeds of 0% if assets are worth nothing in case the firm would fail.
  2. HONMA will earn a ROC equal to 15%, greater than its Cost of Capital. I am assuming that the firm will maintain its alleged competitive advantage (given by its incremental market share and high ROC & ROE) in the long run.

With all these inputs and others not described on this post, the resulting value is shown below:
The value for equity give us Ұ91,856 million which dividing to number of shares 613.26 million, give us Ұ149.78 per share (or HK$10.34) well above the stock price of HK$6.78. 

May 12, 2019

Valuing Caixabank (Spanish Bank) with FCFE Model


1.Story

Caixabank is a spanish retail bank, has a very strong focus on serving clients in Spain 90% and 10% in Portugal thanks to the recent purchase of 100% of the Portuguese bank BPI. The bank provides traditional banking services to Individuals, Small-Businesses, Private Corporations and Public Sector. In 2018 the firm generated a gross income of €8,767 millions and an income before taxes of €2,806 millions.

Caixabank has completed the first strategic plan launched four years ago and have begun a new plan for 2019-2021 horizon.  During the period 2015-2018 (first strategic plan), the company has improved ratios, margins, and market presence as we see in the tables below:


Thanks to the effort of restructuration, Caixabank is running a simple commercial banking system combining physical branches and the digital world, a business model that covers all financial and insurance needs, and that will get more market presence for the company.

2.Valuation

The valuation I proposed is based on a Free Cash Flow to Equity (FCFE) Model. The FCFE are projected and planned in detail for the next 5 years. After 5th year, the bank is assumed to be in a steady state.

The absolute level of the FCFE is a function of Caixabank’s Risk Adjusted Assets (RWA), their growth (g), its Common Equity Tier 1 Capital in terms of RWA (CET1 ratio), and its expected return on equity (ROE). To estimate present values for these FCFEs, we also need to estimate the cost of equity for next years and beyond. For all of these parameters I make the following assumptions:

1. RWA will grow at expected inflation of Euro Zone (+1.80%) forever.

2. The Common Equity Tier 1 Capital Ratio (CET1 Ratio) of Caixabank is 11.80% and the firm revealed its objective for the next 3 years at 12% plus 1% to absorb any potential regulatory impact. After year 3, I assume the ratio will stay around 12%.

3. The firm expect to achieve a return on tangible equity (ROTE) over 12% in 2021 and the current ROTE is 9.3%, it means an increment of 270 basis points. I assume for ROE the same proportional increment, passing from current 8.26% up to 10.66% in 2021. The following years ROE will be at level of 10.66% and, in the steady state, the ROE is assumed to amount to the current average cost of equity of European Banks (estimated in the next point 5).

4. To arrive at the current cost of equity, I use the average beta for the European banking industry (1.16) that reflects Caixabank´s exposure in the retail banking business, in conjunction with the euro risk-free rate of -1.85% and an equity risk premium of 7.90%.

5. To estimate the cost of equity at end of year 5, I will adopt a different way. To illustrate the process, consider the median bank at start of 2019, trading at a price to book ratio of 0.65 and generating a return on equity of 6.68%. Since the median bank is likely to be mature, I will use a stable growth model to derive its price to book ratio:

Plugging in the median bank´s numbers into this equation and using a growth rate equal to the expected inflation (+1.80%), I estimate a cost of equity for the median banks to be 9.31%
So the proxy for the cost of equity in stable steady for Caixabank will be 9.31%, and the Cost of equity will increase progressively since an initial 7.31% up to 9.31%.

The following table summarizes the estimates of net income, FCFEs, Terminal Value, Cost of Equity, and present values, over next five years and beyond:
The sum of all present values give us a value of equity of €29,181 millions, and dividing by the current number of shares outstanding (5,981 million), I can obtain the value of equity per share:

In May 2019, Caixabank was trading at €2.77 and looked undervalued

March 16, 2019

TGS-Nopec (TGS) Valuing a Commodity Company

TGS-Nopec is a norwegian geophysical company which provides of marine seismic data for E&P companies. The firm could be classified as a commodity company as oil price impact not only in revenues and earnings but also reinvestment and financing costs.

Valuation

When valuing this type of companies, the danger of focusing on the most recent fiscal year is that the resulting valuation will depend in great part on where we are in the cycle (oil price). If the most recent year was a boom (or down) year, the value will be high (or low). Consequently, normalization with commodity companies has to be built around a normalized commodity price.

So, what is a normalized price for oil? We will use expected oil prices from the forward and futures markets. We know that these forward and futures prices only offer the illusion of forecasts, because they are tied to the current oil price. The advantage of this approach is that it comes with a built-in mechanism for hedging against oil price risk. An investor who believes that a company is undervalued but is shaky on what will happen to oil prices in the future can buy stock in the company and sell oil price futures to protect herself against adverse price movements.

Figure 1 shows TGS´s EBIT as a function of the oil price (Real Brent ($/barrel)) each year from 2002 to 2018.

The EBIT clearly increases (or decreases) as the Brent increases (or decreases). We regress the EBIT against the Brent over the period and obtain the following:
To get from EBIT to equity value at TGS, we make the following assumptions:
  • TGS´s EBIT will grow at 2% in perpetuity from next year.
  • We estimate a bottom-up beta of 1.08 for TGS. Then we use the treasury bond rate of 2.61% and an equity risk premium of 6.63% to estimate a cost of equity:
Cost of Equity = 2.61% + 1.08 (6.63%) = 9.79%
  • TGS has a market value of debt of $55.27 million (after operating lease adjustment) and a market value of equity of $2,769.89 million, resulting in a debt ratio of 98%. Its cost of debt is expected to be 8.72%, reflecting a default spread of 6.11% over the risk free rate. Using a marginal tax rate of 23% (rather than the effective tax rate), we estimate a cost of capital of 9.73% for the firm:
Cost of Capital = 9.79% (0.98) + 6.72% (0.02) = 9.73%
  • TGS will continue forever with same ROIC and cost of capital currently estimated in the base year.
TGS reported EBIT of $230.0 million in 2018, but that reflects the fact that the average oil price during the year was $70.94. Actually, the expected oil price (future Brent) has dropped to $66.86, and the EBIT for the coming year should be lower. Using the regression results, the expected EBIT at this oil price is $172.42:
EBIT (Normilized) = -92.08 + 3.956 ($66.86) = $172.42

This EBIT has to be adjusted to operating leases reported in 2018, resulting $170.95 million. This EBIT translate into a ROIC of 12.54% and a reinvestment rate of 15.94%, based on a 2% growth rate.
Reinvestment Rate = g/ROIC = 2%/12.54% = 15.94%


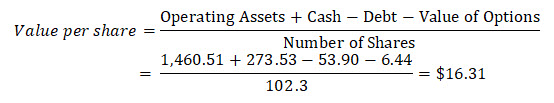
Adding the current cash balance ($273.53 million), subtracting debt with the operating lease adjustment ($53.90 million), subtracting the value of options ($6.44 million), and dividing by the number of shares diluted (102.3 million) yields the value per share of:


At its current stock price of $27.79, the stock looks highly overvalued.

Simulation

Because the earnings, cash flow, and value of TGS are determined to a great extent by what happens to the oil prices, probabilistic approach could works here. We can use simulations of the oil price to derive the value of TGS. The trickiest part of this simulation is to establish how the inputs to the valuation (earnings, reinvestment, and cost of financing) will change as the price of the oil change.

We will make several steps:
1. Determine the probability distribution for the oil price: Because the value per share is so dependent on the oil price, it would make more sense to allow the oil price to vary and value the company as a function of this price 

2. Link EBIT to oil price: We used the regression results from earlier

3. Estimate the value as a function of EBIT: As the EBIT changes, there two levels at which the value of the firm is affected. The first is that lower EBIT, other things remaining equal, lowers the base FCFF, and reduces value. The second is that ROIC is recomputed, holding the capital invested fixed, as the EBIT changes. As EBIT declines, the ROIC drops and the firm will have to reinvest more to sustain the stable growth rate of 2%. While we could also have allowed the cost of capital and the growth rate to vary, we feel comfortable with both numbers and have left them fixed.

4. Develop a distribution for the value: We ran 10,000 simulations, letting the oil price vary and valuing the equity value per share in each simulation. The results are summarized in Figure 2:

The average value per share across the simulation was $12.80, with a minimum value of $0,46 and a maximum value of $41,27. The current stock price is $27,79 and there is 96% chance that the value will be less.

Conclusion

Commodity companies are hard to value because the uncertainty and volatility are, at least for me, greater than in any other type of companies.

As many investors try to make pricing (multiples) with TGS-Nopec that probably yield an undervalued company, my faith in valuing (discount cash flows) is stronger than pricing and 
I would not buy shares in a firm overvalued.

Knowing that this is a firm with great advantages that we have not analyzed in this post, I would be patience and wait until the opportunity arises.


February 23, 2019

Gym Group Plc (GYM) should cut pay dividends


Since IPO in 2014, GYM is a public company traded in LSE with a current market capitalization about ₤269 million. Founded in 2007 by the current CEO John Treharne, the company provides 147 low cost gyms across the UK and is considered as a high growth firm by many investors (as well as by me).


If GYM is in a growth stage of its life cycle, as we see in the figure above, I would not expect neither dividends nor buyback stocks because it is highly probably that the company need the cash to great investment opportunities, but GYM don’t follow this expectation: the firm initiated a token dividend in 2016 of ₤0.32 million, increasing it to ₤1.35 million in 2017 and all seems that it´s going to increase again in 2018 as we see in the last TTM ₤1.54 million (we don´t have yet the results of 2018).

Is GYM right about this dividend policy? The acid test to answer this question is estimation of how much cash a firm can afford to return to its stockholders (or the Free Cash Flow to Equity).

In order to come to a conclusion, I will begin with the P&L statements reported by the company in the last four-five years, including the last TTM:


The next step is the adjustment and normalization of this statement, and several adjustments are needed:
  1. One-time charge from other income in year 2015, is eliminated.
  2. Amortizable Intangibles is non tax deductible item and should be added back to the revenues. Only tax deductible depreciation and amortization counts.
  3. Our tax should be in accordance with a normalized effective tax rate

With all these pieces, we come to our Net Income adjusted and normalized:


My next step is estimations of incremental in non-cash working capital, difference between debt issued and debt repaid, and computation of capital expenditures:

  1. The Change in non-cash working capital year by year is described as follow:
  2. For the difference between debt issued and debt repaid, I will take a proxy through the incremental book value of debt reported in the balance sheet
  3. In estimating capital expenditure I will not distinguish between internal investment (maintenance capex) and external investment (growth capex). The capital expenditure of a GYM, therefore, need to include all purchases, business combination, etc, reported as cash flow from investing activities.

Finally, with all these pieces attached, the result is as follow:


As we see in the table above, the Free Cash Flow to Equity is negative and some years (e.g. 2015) very negative. Thus, GYM don´t have capacity to return cash to stockholders and should stop what it is doing.

But, why GYM pay dividens, as it should not do it? a possible answer could be that high growth firms are sometimes advised by the banker to initiate dividends because it increases the potential stockholder base for the company and, by extension, the stock price .. and that´s true, for example look at pension funds, pension funds cannot buy stocks that do not pay dividends. Thus, the banker makes the suggestion to pay a token dividend, a small dividend that increase the demand of the stock and push up stock prices. It sounds awful good, but that is the way the problems get started. When the stockholders receive for the first time dividends, what investors expect the next year?, of course more dividends!, the firm can´t blame investors.

In summary if the firm cannot pay dividends, the firm should not get start this process, it seems easy to say, but hard to stick with this rule.